A home on pilings along 30A can usually be insured, but eligibility comes before price. Companies check the piling material, the home’s age, the distance to the Gulf and what is enclosed at ground level. Flood is a separate policy, and first floor height is a major rating factor. We quote these homes with the carriers we represent.
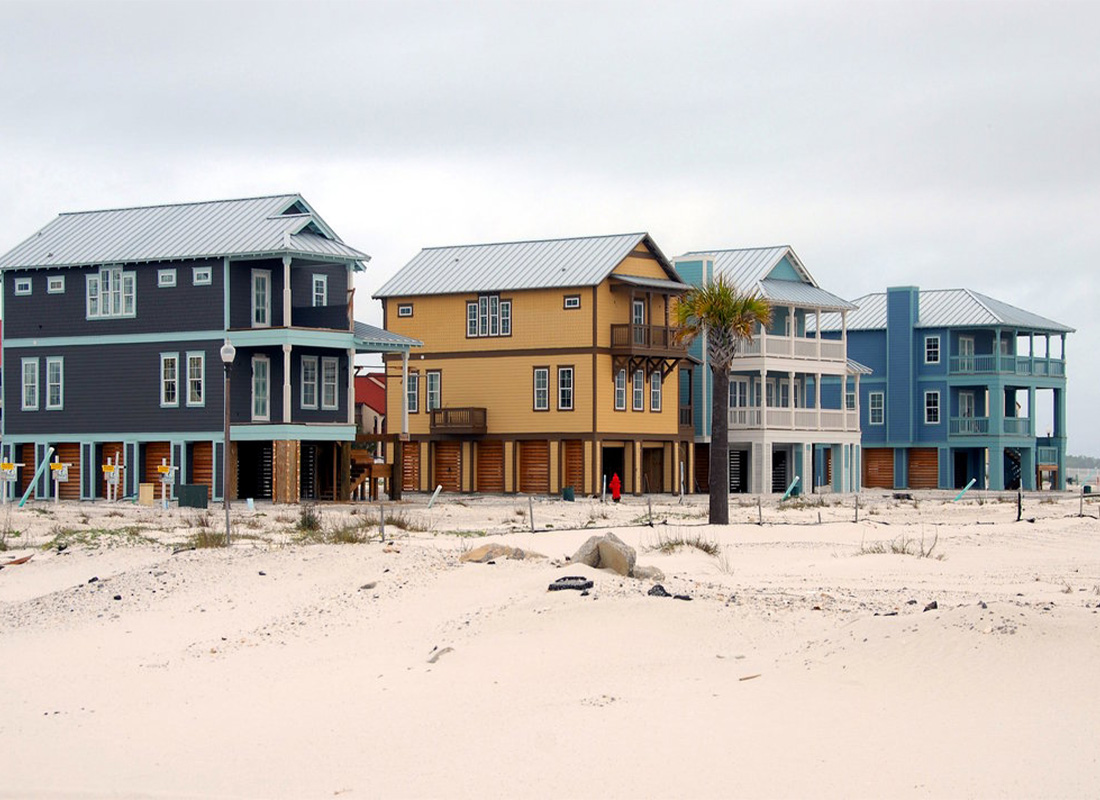
Homes on pilings on 30A, as of November 2026
-
In V and VE flood zones the Florida Building Code requires an open foundation of piles, columns or piers, no fill for structural support, and the bottom of the lowest horizontal structural member at least 1 foot above the base flood elevation. A county can require more, so check with Walton County before you build, elevate or substantially improve.
-
Below the elevated floor, an enclosure may be used only for parking, building access or storage, built of flood damage resistant materials. Breakaway walls designed for 10 to 20 pounds per square foot can follow the prescriptive rules, and stronger walls need certification by a registered engineer or architect (FEMA Technical Bulletin 9, September 2021).
-
Under FEMA’s Risk Rating 2.0, a federal flood premium is rated on the building itself, including first floor height, foundation type, distance to water, ground elevation and rebuild cost. The flood zone still decides whether a federally backed mortgage requires flood insurance.
-
Walton County’s 2024 floodplain management report lists a Class 6 rating in FEMA’s Community Rating System for unincorporated Walton County. Under Risk Rating 2.0 that rating takes one fifth off the rated part of most federal flood premiums across the participating community, not only in the high-risk zones; fees and surcharges are not discounted.
-
The flood insurance rate map for unincorporated Walton County took effect December 30, 2020, and letters of map revision have changed parts of some panels since.
-
The Coastal Barrier Resources Act bars federal flood insurance for structures built or substantially improved after a mapped unit’s prohibition date. Walton County has five mapped units: Moreno Point (P32) and Four Mile Village (P31A), dated October 1, 1983; Deer Lake (FL-94) and Draper Lake (FL-96), dated November 16, 1990; and the Grayton Beach Otherwise Protected Area (FL-95P), dated November 16, 1991 (42 U.S.C. 4028). Areas added to a unit later carry later dates, so the date for an address comes from the CBRS Mapper.
-
Florida’s wind mitigation form, OIR-B1-1802, was revised for inspections on or after April 1, 2026. It records the building code the home was built under and scores the roof and the openings; it has no question on the foundation or the pilings (sections 627.0629 and 627.711).
-
On a home insured for 250,000 dollars or more, Florida law does not require a company to offer the flat 500 dollar hurricane deductible, so the options it must offer are shares of the dwelling limit (section 627.701).
Can a home on pilings on 30A be insured?
Usually, yes. On a slab house inland the conversation starts with coverage and price. On a piling home near the Gulf it starts with whether a company will write it at all, because wind gets under an open foundation and the ground level is open or only partly enclosed. Underwriters look first at the piling material and how the posts are set, the home’s age, the distance to the Gulf and the height of the pilings, what is enclosed at ground level and how it is used, and the roof and its wind mitigation features. As of November 2026, most programs we place that write homes on pilings prefer concrete or steel pilings, and several accept wood pilings only on newer homes, roughly the last 10 to 25 years depending on the program, or only when the wood posts are set in concrete, subject to underwriting.
A decline from one company is not the last word. Piling rules differ from company to company, so a home one program will not write may fit another, and a home you rent to guests usually belongs on a dwelling policy, not a homeowners policy. As of November 2026, at least one admitted company we represent now accepts some homes on wood pilings, with conditions on the home’s age or how the posts are set, an inspection and an added charge on the all other perils premium, subject to underwriting. Through 2024 and 2025 homes on wood pilings were hard to place, so a coastal home placed in those years is worth quoting again rather than renewing on autopilot.
What happens if we enclose or finish the ground level?
Below the elevated floor the rules are tight. An enclosure may be used only for parking, building access or storage, built of flood damage resistant materials, with utilities and ductwork above the required elevation, and its walls in a V zone have to be designed to break away under flood loads.
Finishing the ground level into a game room, a bunk room or conditioned space changes two things at once. It can put the building out of step with the county’s floodplain rules, and it changes how flood insurance treats the space. On an elevated home in a VE or AE zone built after the community’s first flood map, a federal flood policy covers only a short list of items below the elevated floor, such as the pilings and foundation, attached stairs, utility equipment like the water heater and air conditioning, and cleanup, and very little of what is kept there. An enclosure also raises the federal flood premium through the foundation type, with or without breakaway walls (FEMA Technical Bulletin 9). Price the insurance consequence before you build it out. Our post on coverage limits under an elevated building goes further.
How is flood insurance rated on an elevated home?
Under Risk Rating 2.0 the rate comes from the building, and first floor height is one of the strongest factors. FEMA’s April 2022 discount guide illustrated it with a crawlspace home whose first floor sat 3 feet above grade, which rated a little more than a fifth lower than the same building at grade. That is FEMA’s illustration for one foundation type, not a figure for your house. An elevation certificate is not required to buy a federal flood policy, but it can lower the premium by documenting a first floor higher than FEMA’s estimate, and private flood companies often ask for one.
Between the VE zone and the Limit of Moderate Wave Action line, the building code commonly calls for V zone style construction. Risk Rating 2.0 gives no zone discount for building to that standard, but the height and foundation it produces still feed the rate. A federal flood policy usually waits 30 days to start and tops out at 250,000 dollars on the building and 100,000 dollars on contents. A second home or a rental pays a 250 dollar yearly federal surcharge instead of 25 dollars, and its building claims are paid at actual cash value. Our flood insurance page covers federal and private flood.
Which 30A addresses cannot buy federal flood insurance?
Under the Coastal Barrier Resources Act, federal flood insurance is not available for a structure built or substantially improved after its unit’s prohibition date. It is not a price penalty; the federal policy simply cannot be written. Besides the Walton units listed above, mapped units sit at Phillips Inlet, just across the line in Bay County, and the Moreno Point units reach into Okaloosa County at Destin. These are mapped segments, not whole towns, so a unit near a community does not mean every address in it is affected.
In a System Unit, a structure that was already insured and is then substantially improved or damaged by more than half its market value can lose its federal policy. In an Otherwise Protected Area, a structure built or substantially improved after the prohibition date can get federal flood insurance only if it is used in a way consistent with the purpose the area protects, with documentation. The BEACH Act (Public Law 118-117, November 25, 2024) redrew the Moreno Point maps, removing about 30 structures and two condominium buildings, and redrew the Grayton Beach and Draper Lake map to remove about an acre added in error in 2006, including a structure in Santa Rosa Beach. The same law calls for federal sale and lease disclosure rules for these areas; as of November 2026 they had not taken effect.
The act limits federal flood insurance. Whether a private flood company will write a home in a mapped unit is a separate underwriting question we can check. The controlling map is the U.S. Fish and Wildlife Service’s CBRS Mapper, not the FEMA flood map, so we check it address by address.
Does a home on pilings earn wind mitigation credits?
The wind mitigation form gives no credit for the pilings. It records the building code the home was built under and scores the roof covering, roof deck attachment, roof to wall connection, roof shape, secondary water resistance and opening protection. Elevation is not a wind mitigation item; it is one of the biggest flood rating factors. On an elevated home near the Gulf, documented opening protection is usually the credit worth chasing, and a report is good for up to five years if the home has not materially changed. Our post on wind mitigation credits explains each one.
The hurricane deductible is the other number to understand. On a home insured for 600,000 dollars, the smallest share option the law requires a company to offer works out to 12,000 dollars; as of November 2026, at least one company we represent offers smaller or flat options, subject to underwriting. The hurricane deductible runs on a calendar year, so a later hurricane that year carries whatever is left of it or the all other perils deductible, whichever is greater (section 627.701). For this purpose a hurricane starts when the National Hurricane Center issues a hurricane warning for any part of Florida and ends 72 hours after the last hurricane watch or warning for any part of Florida ends (section 627.4025). Our post on hurricane deductibles on 30A walks through the math.
How much does insurance cost for a home on pilings on 30A?
It is quoted per address, not published. The price turns on the dwelling limit, the construction and piling material, the home’s age, the roof and its wind mitigation features, the distance to the Gulf, the hurricane deductible you choose and your claims history. Two elevated homes a few streets apart can price very differently. Some piling homes place with surplus lines companies, which are not protected by the Florida Insurance Guaranty Association, and we point that out when we quote one. Flood is priced separately on the building’s own elevation and characteristics. Every quote is subject to underwriting.
What if my elevated home is a vacation rental?
Many of the piling homes on 30A are rented, and renting changes the policy. A home rented to guests usually belongs on a dwelling policy rather than a homeowners policy, and Florida licenses a home rented to guests more than three times in a calendar year for stays of less than 30 consecutive days, or advertised as regularly rented for such stays, as a vacation rental. Construction and occupancy are underwritten separately, so both have to clear. Our short-term rental insurance page covers guest rentals, and our landlord insurance page covers annual leases.
Talk to us before you buy, build or renew
To tell you whether an elevated home can be placed and on what form, we need the address, the year built, the piling material and how the posts are set, the height of the first floor, what is enclosed at ground level and how it is used, the roof age, and a wind mitigation report from the last five years. An elevation certificate helps on the flood side. Hurricane season starts June 1, insurance companies commonly stop binding new coverage once a watch or warning goes up, and a federal flood policy usually waits 30 days, so do not wait for a storm.
Call the office at 850-622-5283 and ask for Alex Reber, Erica Johnson, Chris Jayne, or Trista Cordell, Fuller Insurance LLC, Florida license L039483. You can email the address and your declarations page to hello@fuller.insure or fill in the quote request form on this page. The office is at 4821 US Highway 98 W, Suite 103, Santa Rosa Beach, FL 32459, open 9 to 4, Monday through Thursday.
Sources for this page: sections 509.013, 627.0629, 627.4025, 627.701 and 627.711 of the 2026 Florida Statutes; the Florida Division of Emergency Management’s January 2024 guidance on flood provisions of the Florida Building Code; FEMA Technical Bulletin 9 (September 2021), the NFIP Flood Insurance Manual, the Risk Rating 2.0 discount guide (April 2022) and the Standard Flood Insurance Policy Dwelling Form (44 CFR Part 61); Walton County’s 2024 floodplain management progress report; 42 U.S.C. 4028, Public Law 118-117 and the U.S. Fish and Wildlife Service’s Coastal Barrier Resources System pages; Florida OIR’s wind mitigation resources; Security First’s public product page; each read November 8, 2026. Terms described as programs we place are as of November 2026. Your own policy’s wording controls, and every quote is subject to underwriting.
Coastal & Piling Home Insurance
Can a house on wood pilings be insured on 30A?
Often, yes. Eligibility depends on the piling material and how the posts are set, the home’s age, the distance to the Gulf, the height of the pilings and what is enclosed at ground level, and the rules differ from company to company. As of November 2026, most programs we place prefer concrete or steel pilings, and several accept wood pilings only on newer homes or only when the posts are set in concrete, subject to underwriting. As of November 2026, at least one admitted company we represent now accepts some homes on wood pilings, with conditions on the home’s age or how the posts are set, an inspection and an added charge, subject to underwriting. Elevated homes are commonly inspected, and every placement is subject to underwriting.
One company declined my piling home. Does that mean nobody will write it?
Not necessarily. Piling rules differ from company to company, so a home one program declines may fit another, and a rented home usually belongs on a dwelling policy rather than a homeowners policy. Ask why it was declined, then check the form and the submission before you accept the answer.
We enclosed the ground level of our beach house. Does that affect our insurance?
It can affect both your floodplain compliance and your flood insurance. Below the elevated floor, an enclosure may be used only for parking, building access or storage. On an elevated home in a VE or AE zone built after the community’s first flood map, a federal flood policy covers only a short list of items there, and an enclosure raises the federal premium through the foundation type, with or without breakaway walls. Price the insurance consequence before you finish out a ground level.
Why is my flood premium so different from my neighbor's on the same street?
Because FEMA’s Risk Rating 2.0 rates the building, not the flood zone. First floor height, foundation type, distance to water, ground elevation and rebuild cost all feed the rate, so two houses a few lots apart can rate very differently if one sits higher or has its equipment above the first floor. The flood zone still decides whether a federally backed mortgage requires flood insurance, and in unincorporated Walton County the Community Rating System discount applies to most federal flood policies, in and out of the high-risk zones.
Do I need an elevation certificate for a piling home on 30A?
Not to buy a federal flood policy. You can still submit one, and it can lower the premium by documenting a first floor higher than FEMA’s estimate. It is generally still needed for community compliance on newer buildings in A and V zones and supports a Letter of Map Amendment, and private flood companies often ask for one, so if you have it, send it.
Do pilings count on a Florida wind mitigation inspection?
No. Florida’s wind mitigation form records the building code the home was built under and scores the roof covering, roof deck attachment, roof to wall connection, roof shape, secondary water resistance and opening protection; it has no question on the foundation or the pilings. Elevation matters on the flood side instead. On an elevated home near the Gulf, documented opening protection is usually the credit worth chasing.
Can I buy federal flood insurance in a coastal barrier zone on 30A?
Generally not for a structure built or substantially improved after the unit’s prohibition date; in an Otherwise Protected Area, a structure used in a way consistent with the area’s purpose can still qualify, with documentation. Walton County has five mapped coastal barrier units, including Deer Lake, Draper Lake and the Grayton Beach Otherwise Protected Area, and the controlling map is the U.S. Fish and Wildlife Service’s CBRS Mapper, checked address by address. The law limits federal flood insurance; whether a private flood company will write the home is a separate underwriting question.
We rent our elevated 30A house by the week. Does that change the policy?
Yes. A home rented to guests usually belongs on a dwelling policy rather than a homeowners policy, and Florida licenses a home rented to guests more than three times in a calendar year for stays of less than 30 consecutive days, or advertised as regularly rented for such stays, as a vacation rental. Construction and occupancy are underwritten separately, so the home has to clear both.
Let’s Get Started
Coastal & Piling Home Insurance Quote Request
"*" indicates required fields
Don’t like forms? Contact us at or email us.