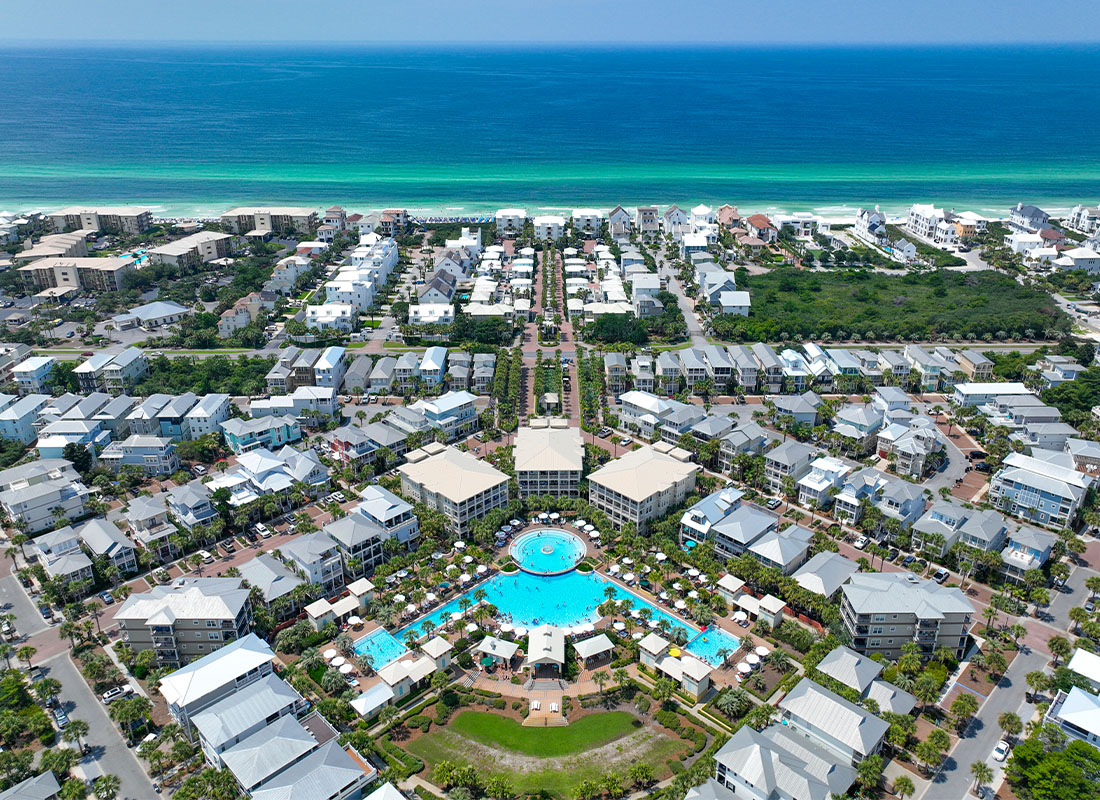
Fuller Insurance writes commercial coverage for property management companies across 30A and the Emerald Coast — Santa Rosa Beach, Blue Mountain Beach, Grayton, WaterColor, Seaside, Seagrove, WaterSound, Seacrest, Rosemary Beach, Inlet Beach, Miramar Beach, and Destin, throughout Walton, Okaloosa, and Bay Counties. We insure the firms that manage short-term and vacation rentals, long-term rentals, and single-family-home and townhome homeowners associations, along with commercial property managers. Your business carries a very different set of risks than the owners whose properties you manage. When a vacation guest is injured at a home in your care, when an employee mishandles rent you hold in trust, or when a property you manage falls out of step with local code, the claim can come to your firm as well as the owner — and the owner’s policy will not defend or pay for your business. A property-management program has to answer your firm’s own exposure: general liability, a professional liability form built for management operations, crime and fidelity, workers’ compensation, commercial auto, and cyber, placed with carriers we represent that will write a firm on the coast.
Property manager professional liability is the coverage most firms are missing
Your general liability policy pays for third-party bodily injury and property damage — a guest slips on a pool deck, a child’s hand is caught in a pool-gate latch, someone falls on a stairway at a property you manage. We have seen every one of those claims on 30A. What general liability does not pay for is a claim that you failed to perform your management duties: a home you manage did not meet code, a maintenance issue you were responsible for led to a loss, or an owner lost rental income because of something your firm did or did not do. That is professional liability — errors and omissions — and it is the single most common gap we find on a management firm.
A property manager needs a policy written for management operations, not a generic miscellaneous errors-and-omissions form. We place property-manager professional liability through specialty carriers such as Markel, Hiscox, and USLI. The form matters as much as the carrier: we look for one that includes contingent bodily injury and property damage — the coverage that responds when a guest is injured at a property you manage and alleges you failed to maintain it. Many off-the-shelf errors-and-omissions forms exclude it or cap it at a low sublimit, so we confirm it on the specific policy before you bind. All terms are subject to underwriting.
Crime and fidelity: protecting the rent you hold in trust
If you employ staff and hold owners’ rents in a trust account, you carry the risk that an employee steals those funds. Crime and fidelity coverage — employee dishonesty — is what pays that loss, and it is one of the coverages management firms overlook most often. We place it through carriers we represent, including Auto-Owners and Liberty Mutual, at limits that reflect the balances you actually hold in trust rather than a token default.
General liability, property, and the rest of the package
Around those two coverages sits the rest of a management firm’s program: general liability for third-party injury and damage, commercial property for your office, contents, and business income, hired and non-owned auto for staff moving between properties, workers’ compensation once you cross Florida’s employee threshold, a commercial umbrella over the top, and cyber liability if you take reservations or payments online. We can package most of this through carriers we represent such as Auto-Owners or Frank Winston Crum. For a firm that would rather carry one policy than several, USLI offers a property-managers package that can bundle general liability, property, professional liability, crime, hired and non-owned auto, and employment-practices liability into a single program. Coverage is subject to underwriting.
The coastal packaging problem, and how we get around it
This is where most agencies stop and a coastal management firm ends up with gaps. Standard package markets often decline a 30A address on proximity to the water, construction type, and year built. Here is how we solve it: we write the Frank Winston Crum commercial package for the general liability, property, and workers’ compensation with wind and hail excluded from the property coverage — which is what lets an admitted market accept a coastal risk — and we place a separate wind-only policy through a wholesale broker to cover the hurricane and wind exposure on the property. Crime, hired and non-owned auto, and professional liability can be added to the package for eligible classes. Auto-Owners can also round out a program with a waiver of subrogation at no additional cost and blanket additional-insured status, two endorsements that many management agreements require you to carry. Flood is always covered separately. All of this is subject to underwriting and each carrier’s appetite.
The property managers we write, and the ones we don’t
We write general property managers: short-term and vacation-rental management companies, long-term rental managers, single-family-home and townhome homeowners-association managers, and commercial property managers. We do not insure condominium associations or condominium buildings. Condominium associations are a specialized, high-value coastal placement shaped by the recent Florida condo statutes, and we leave that market to others so we can do right by the managers and owners who make the decisions themselves. If you manage single-family-home or townhome communities, the board often defers to your management company on insurance — and that direct relationship is exactly what we are built for.
Built on 30A, for the Emerald Coast
We are an independent agency in Santa Rosa Beach, working Walton, Okaloosa, and Bay Counties every day, and we know which carriers will write a management firm at a coastal address versus decline it. Because the vacation-rental market is the core of what we do, we also write the dwelling-fire and condo-unit policies your owners’ rental properties need — so the homes you manage and the firm that manages them can be covered under one roof.
Talk to a local agent about your management firm
Every property-management account we write is handled by a licensed agent who knows this coast. Call us at 850-622-5283 or request a quote, and ask for Chris Jayne, Trista Cordell, or Alex Reber.
Property Manager
Does a property manager need its own insurance if the owners already insure their properties?
Yes. A guest injury or a management dispute can name both the property owner and the management firm, and the owner’s policy will not defend or pay for your business — it covers the owner. Your firm’s own general liability and professional liability respond to your firm’s exposure. Property managers and owners carry separate risks, which is why a management firm needs its own program.
What is property manager professional liability, and why isn't general liability enough?
General liability covers third-party bodily injury and property damage, such as a guest injured at a property you manage. Professional liability — errors and omissions — covers claims that you failed to perform your management duties: a managed home that did not meet code, a maintenance failure you were responsible for, or an owner’s lost rental income. A general liability policy was never designed to answer those claims, and the professional liability form should be written specifically for property-management operations, ideally including contingent bodily injury and property damage. Coverage is subject to underwriting.
What coverage protects the rent I hold in trust for owners?
Crime and fidelity coverage — specifically employee dishonesty — pays for funds an employee steals, including owners’ rents held in a trust account. If your firm has employees and handles owner money, this is one of the most important and most overlooked coverages you can carry. We place it through carriers we represent, including Auto-Owners and Liberty Mutual, at limits that match the balances you actually hold.
Can a property management company get coverage on a coastal 30A property?
Yes. Coastal addresses cause most standard package markets to decline on proximity to the water and construction, so we take a different route: we write an admitted commercial package for the general liability, property, and workers’ compensation with wind and hail excluded, and place a separate wind-only policy through a wholesale broker for the hurricane exposure. Crime, professional liability, and hired and non-owned auto can be added for eligible classes. Flood is always covered separately. All coverage is subject to underwriting and carrier appetite.
Does Fuller Insurance write condominium associations?
No. We do not insure condominium associations or condominium buildings. We write general property managers — short-term and vacation-rental managers, long-term rental managers, single-family-home and townhome homeowners-association managers, and commercial property managers. Condominium associations are a specialized coastal placement shaped by recent Florida condo law, and we focus instead on the managers and owners who make the decisions directly.
Which property managers does Fuller Insurance work with in Walton, Okaloosa, and Bay Counties?
We write short-term and vacation-rental management companies, long-term rental managers, single-family-home and townhome homeowners-association managers, and commercial property managers across 30A and the Emerald Coast — Santa Rosa Beach, Grayton, Seaside, WaterColor, WaterSound, Rosemary Beach, Inlet Beach, Miramar Beach, and Destin. Because vacation rentals are the core of our book, we can also write the dwelling-fire and condo-unit policies your owners’ rental properties need.
Let’s Get Started
Property Manager Insurance Quote Request
"*" indicates required fields
Don’t like forms? Contact us at or email us.