HO6 condo insurance for Santa Rosa Beach & 30A: what it covers
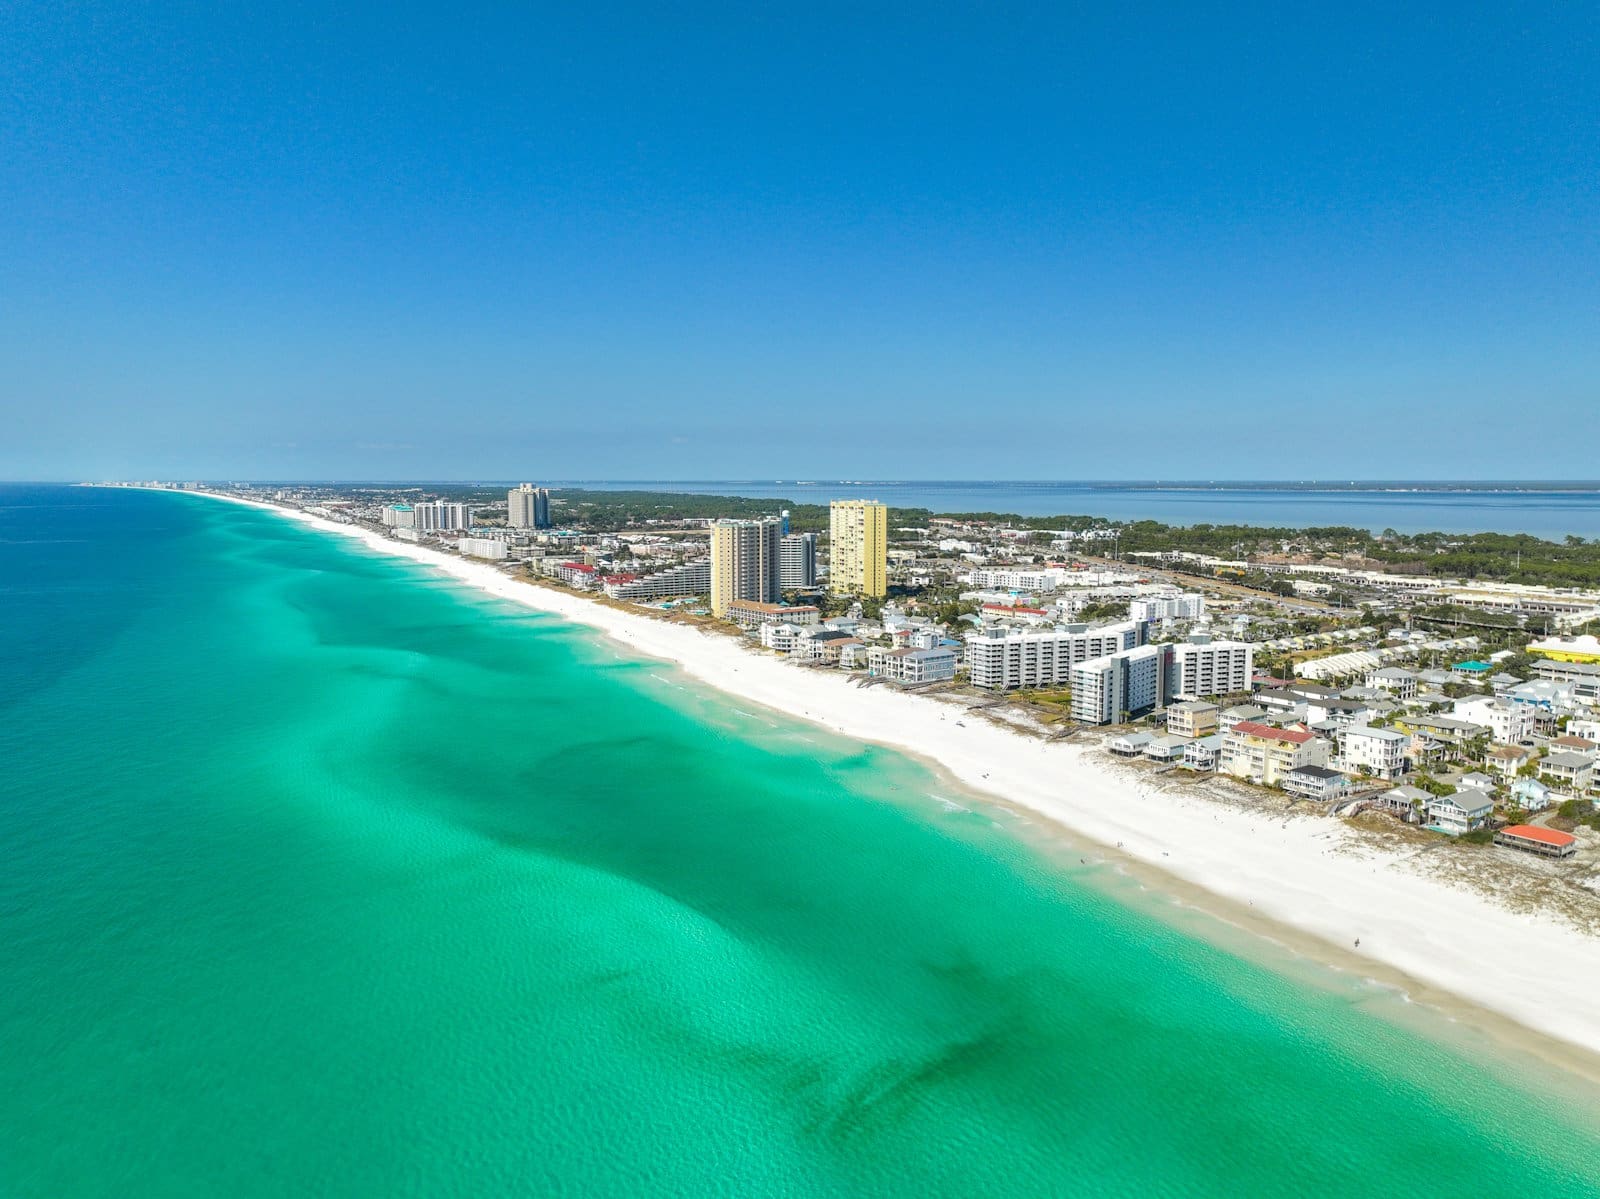
If you own a condo on 30A — Santa Rosa Beach, Seagrove, Blue Mountain Beach, Rosemary, Inlet Beach, or anywhere along the Emerald Coast — an HO6 policy covers the part of your unit your association’s master policy doesn’t: your interior build-out (drywall, flooring, cabinets, fixtures), your personal property, your personal liability, loss of use if the unit is uninhabitable after a covered loss, and your share of an association loss assessment. Most Florida coastal condo master policies are “bare walls-in,” which leaves everything from the studs inward to you. We place HO6 coverage with the Florida coastal carriers we represent — including admitted markets like American Integrity and Frontline — and we’ll help you match your Coverage A limit to your actual build-out instead of a default number. (Renting your unit short-term on 30A? The right policy may be a DP3 rather than an HO6 — we cover that distinction below.)
What does an HO6 condo policy cover?
An HO6 policy insures the part of your condo you’re responsible for — the interior, your belongings, and your liability — plus coverages built specifically for condo ownership:
- Coverage A — Interior / build-out: the finished interior you own — drywall, flooring, cabinets, countertops, built-ins, and upgrades. Under a “bare walls-in” master policy, that’s everything from the studs in.
- Coverage C — Personal property: furniture, electronics, clothing, and contents.
- Coverage D — Loss of use / loss of rents: living expenses, or fair rental value if you rent it, when the unit is uninhabitable after a covered loss.
- Coverage E — Personal liability: claims against you for injury or damage you’re responsible for — including water that escapes your unit into a neighbor’s.
- Coverage F — Medical payments: smaller medical bills for a guest hurt in your unit, regardless of fault.
- Loss assessment: your share of an association special assessment after a covered loss — with important limits we explain below.
Limits, deductibles, and terms vary by policy and carrier, and are subject to underwriting.
Your master policy vs. your HO6: who covers what
Your condo association carries a master policy that insures the building and common elements — Florida law requires the association to insure those at replacement cost (Fla. Stat. 718.111). What that master policy leaves to you depends on its type:
- Bare walls-in (most common on the coast): the association covers the structure out to the unfinished drywall; you insure everything from the studs in — finishes, fixtures, cabinets, flooring, and your contents. This is where your HO6 Coverage A does the most work.
- Single entity: the association covers the original fixtures and finishes as built; you insure your upgrades plus personal property.
- All-in (all-inclusive): the association covers the building and unit fixtures, including some improvements; you still insure your personal property and liability.
Master policies almost always carry a separate — and often large — hurricane or wind deductible, and after a storm your share of that deductible can come back to you as an assessment. Here’s the important part: we don’t review or have access to your association’s master policy or condo documents. Before you set your HO6 limits, get your master policy’s coverage type and its hurricane deductible from your association or management company — that’s what tells us how much Coverage A and loss assessment you actually need.
Loss assessment: what it actually pays (and what it doesn’t)
Loss assessment coverage pays your share of a special assessment your association levies after a loss — but only when that loss is a peril your own HO6 would cover, such as hurricane or wind damage to the building. It can also pick up your assessed share of the master policy’s deductible after a covered storm, depending on your policy’s wording.
What it does not pay for is just as important: loss assessment does not cover special assessments for routine maintenance, deferred repairs, reserve funding, or structural, engineering, and milestone-inspection (SIRS) work. Those are the assessments making headlines on older coastal buildings — and a loss-assessment limit won’t touch them.
Florida law builds in a minimum: every HO6 must include at least $2,000 of loss assessment coverage, with a deductible no higher than $250 (Fla. Stat. 627.714). You can usually raise that limit — commonly into the $5,000–$10,000 range — though availability varies by carrier and is subject to underwriting. We’ll help you set a limit that fits your building, not a default.
Milestone inspections, SIRS, and special assessments on older coastal buildings
After the 2021 Surfside collapse, Florida tightened condo safety law. Buildings three stories or taller must complete a milestone structural inspection at 30 years — or at 25 years if they’re within three miles of the coast, which covers nearly every beachfront condo on 30A and the Emerald Coast. Associations must also complete a Structural Integrity Reserve Study (SIRS) and can no longer waive reserves for key structural components (HB 913 set the initial SIRS deadline at December 31, 2025).
When an inspection or reserve study turns up needed structural work, the association funds it through a special assessment — and on older coastal buildings those can be substantial. Reported cases elsewhere in Florida have run from tens of thousands to several hundred thousand dollars per unit (those are extreme news examples, not local averages). Here’s what owners often miss: because these assessments fund maintenance and reserves rather than a covered peril, your HO6 loss-assessment coverage does not pay for them. No amount of loss-assessment limit changes that.
That’s why we tell every 30A condo buyer to ask the association three things before closing: the date and result of its milestone inspection, its SIRS status, and how fully it funds reserves. We can’t insure a structural assessment away — but we can make sure your HO6 is built right for the assessments it can help with (the hurricane and wind losses your building actually faces), and that the rest of your coverage fits an older coastal building. Bring us the association’s numbers and we’ll size it with you.
Renting your condo: HO6 endorsed for rental, or DP3?
Many owners assume renting their condo means a different kind of policy. Usually it doesn’t — it means writing or endorsing your HO6 for the rental. A standard HO6 restricts coverage for a unit that’s regularly rented (your personal property and liability can be excluded during rental periods), so the fix is a rental endorsement — on ISO forms, the Unit-Owners Rental to Others endorsement (HO 17 33) — or a carrier whose HO6 program already allows short-term rental. Either way, you keep the coverage that matters most on the coast: loss assessment, which the dwelling-fire alternative usually doesn’t include.
A DP3 dwelling-fire policy (written with a condominium designation) comes into play in two situations: when a carrier’s program requires the rental on a DP3 rather than the HO6, or when you never occupy the unit at all — a pure investment property. The DP3 covers the rental dwelling and your loss of rents, but it typically does not include loss assessment, so that hurricane-deductible exposure has to be planned for separately.
Which path you land on depends on the carrier as much as the rental itself. Among the Florida coastal markets we represent, Frontline writes condos for owner-occupied, seasonal, and short-term rental use on the HO6 — including loss assessment and loss of use — while Olympus requires short-term rentals on a DP3 with a condo type and a seven-day minimum stay. Others, including Security First, Cabrillo, and Centauri, write the rental condo forms as well, and minimum-stay and occupancy rules vary by carrier and are subject to underwriting. The one constant: the rental use has to be fully disclosed, or a claim can be denied. We go deeper on this on our short-term rental insurance page and in our guide to short-term rental condo insurance.
One honest caveat for any rental: loss-of-rents pays fair rental value while the unit is uninhabitable after a covered loss, which can fall short of peak-season nightly income — so set that limit deliberately. Tell us how you use the unit and we’ll put it on the right form with the right carrier.
Why it’s worth re-shopping your condo insurance now
Florida’s coastal insurance market has been stabilizing. New carriers and fresh capital have entered the state, Citizens has shed hundreds of thousands of policies back to private companies, and more insurers are writing condo and condo-association coverage than they have in years. For owners who were placed during the hard market — or who haven’t compared in a while — that often means more options worth a fresh look.
As an independent agency, we place condo coverage across many of the Florida coastal carriers we represent — admitted markets, and specialty markets when a risk needs them — and match the form to how you use the unit. We’ll also make sure the pieces a single policy can’t cover are accounted for, including a separate flood policy, since your HO6 never includes flood. The goal is the right coverage for an older coastal building, not just a number.
Whether you’re buying, closing on a unit, or just want a second opinion on what you have, send us the basics and we’ll review your options. Start your condo quote above, or call us at 850-622-5283.
Condo (HO6) Insurance FAQ
Is condo (HO6) insurance required in Florida?
It’s not required by Florida law, but your mortgage lender will almost always require it, and your condo association’s bylaws may require a minimum HO6 with a set loss-assessment limit. Even if you own the unit outright, your association’s master policy doesn’t cover your interior finishes, your belongings, or your personal liability — so HO6 coverage is strongly recommended.
What does an HO6 condo policy cover?
An HO6 covers the parts of your condo you’re responsible for: your interior build-out (Coverage A), personal property (C), loss of use or loss of rents (D), personal liability (E), and medical payments (F), plus loss assessment for your share of certain association assessments. In short, it fills the gaps your association’s master policy leaves to you.
Do I need an HO6 or a DP3 to rent my condo?
If you use the condo yourself and also rent it, the usual answer is an HO6 written or endorsed for rental — it keeps coverages like loss assessment that the dwelling-fire form typically drops. A DP3 dwelling-fire policy applies when you never occupy the unit, or when a carrier’s program requires it. Either way, the rental use has to be disclosed to the carrier, or a claim can be denied.
Does condo insurance cover special assessments after a hurricane?
Your HO6 loss-assessment coverage can pay your share of an assessment when it stems from a covered peril — such as hurricane or wind damage to the building. It does not pay for assessments that fund routine maintenance, reserves, or structural and milestone-inspection (SIRS) work, no matter how high your limit is.
How much loss assessment coverage do I need?
Florida requires every HO6 to include at least $2,000 of loss assessment, and many coastal owners raise that limit — commonly into the $5,000–$10,000 range, subject to underwriting. The right amount depends on your building’s master-policy hurricane deductible, so ask your association for that figure and we’ll help you size it.
Do I need flood insurance for my condo?
Yes, separately — an HO6 never includes flood. Your association’s policy (often an NFIP RCBAP) insures the building structure, not your interior finishes, upgrades, or contents, so a separate unit-owner flood policy is recommended, especially for low-floor or Gulf-front units.
Quick Start Condo Insurance Quote
Start now and we’ll be in touch with your condo insurance options.
Start Now
Let’s Get Started
Condo Insurance Quote Request
"*" indicates required fields
Don’t like forms? Contact us at or email us.