Standard homeowners and condo insurance does not cover flood damage, so flood is written as a separate policy. For property in Santa Rosa Beach and along 30A, that’s coverage worth putting in place. As an independent Emerald Coast agency, Fuller Insurance compares private flood — Neptune Flood, Wright Flood, and Flood Risk Solutions among the carriers we represent — against the federal NFIP to fit your specific property and how much coverage you want.
Why flood is a separate policy — and why it matters on 30A
Standard homeowners, condo (HO6), and renters policies exclude damage from flooding — that’s the market standard, which is why flood is written as its own policy. To insure against flood, you generally need a separate policy through either the federal National Flood Insurance Program (NFIP) or the private flood market.
Living outside a mapped high-risk zone doesn’t mean the risk disappears. According to the NFIP, about 29 percent of its flood claims from 2014 through 2024 came from areas outside the high-risk flood zones, and FEMA notes that just one inch of water in an average home can cause roughly twenty-five thousand dollars of damage. Between 2020 and 2024, the average NFIP claim paid more than eighty-two thousand dollars. On the Gulf, that’s meaningful exposure — not a rare event.
Private flood vs. the NFIP: where each one fits
The federal NFIP policy caps building coverage at two hundred fifty thousand dollars and contents at one hundred thousand dollars, does not include loss-of-use or additional living expense coverage, and settles the building of a non-primary residence at actual cash value rather than replacement cost. On a high-value coastal home, those limits can leave real gaps.
Private flood can close those gaps. The Neptune Flood policies we write can add optional coverages such as replacement-cost settlement, temporary living expenses up to fifty thousand dollars, pool repair and refill up to twenty thousand dollars, and coverage for unattached structures — none of which the NFIP includes — often with a shorter waiting period, subject to underwriting. Through Flood Risk Solutions, we can layer excess flood coverage above the NFIP and other private limits; one private placement let us insure a Santa Rosa Beach home to one and a half million dollars in replacement cost, far above the federal cap. Wright Flood, one of the country’s largest NFIP servicers, gives us excess flood insurance options as well and is often the better choice when the NFIP fits your situation. For your specific property, we’ll compare your options and quote the most competitive rate among the carriers we represent, subject to underwriting.
The NFIP is still the better fit in several situations: when you can assume a seller’s existing, grandfathered policy and keep its capped annual increases; when your property qualifies for the Walton County community discount described below; when a private carrier declines an older or ground-level home; or when you want the certainty of the federal program. We weigh both for your situation.
The Florida flood rules that affect you right now
Three current rules change how flood works on the coast:
The Citizens flood mandate. Under Florida law (Section 627.351(6)), if your property is insured by Citizens with wind coverage, flood coverage is required once your dwelling (Coverage A) reaches four hundred thousand dollars or more — that threshold took effect January 1, 2026. By January 1, 2027, the requirement extends to all Citizens personal-residential policies, regardless of flood zone. Condominium unit-owner and tenant-content policies are exempt. Confirm your status at your next Citizens renewal.
The landlord flood-disclosure law. Effective October 1, 2025, Florida Statute Section 83.512 requires landlords to give a prospective tenant a separate flood-disclosure document before signing a residential lease of one year or longer. It does not apply to short-term or vacation rentals under a year. This is general information, not legal advice, and Fuller does not draft the disclosure — but if you own long-term rentals, it’s on your radar now.
FEMA’s Risk Rating 2.0. FEMA now prices flood on a home’s elevation, first-floor height, distance to water, and construction — the flood zone no longer sets the premium, though it still determines whether coverage is federally required. Elevated coastal homes built on pilings, with mechanical equipment above the first floor, can earn meaningful rate relief. If you’re buying, ask whether you can assume the seller’s existing NFIP policy to keep its capped-increase pricing rather than starting at the full-risk rate.
Bind before the storm — the 30-day rule and the named-storm freeze
Two timing rules catch coastal buyers off guard. A new NFIP policy generally takes 30 days to take effect, with limited exceptions such as coverage required to close a loan. Private flood often binds faster. But once a storm is named and watches or warnings go up for our area, most carriers — including many private flood markets — suspend new coverage and increases until the threat clears, usually within a day or two of it passing. The practical takeaway: put flood in place before a storm is on the way, not while one is approaching.
What flood really looks like on 30A
Flood zones here can change block to block. A single 30A neighborhood can include Zone X, Zone AE, and Zone VE within a few streets, and a Gulf-front or dune-lake lot rates very differently from one a block inland — so we rate each quote to the specific address.
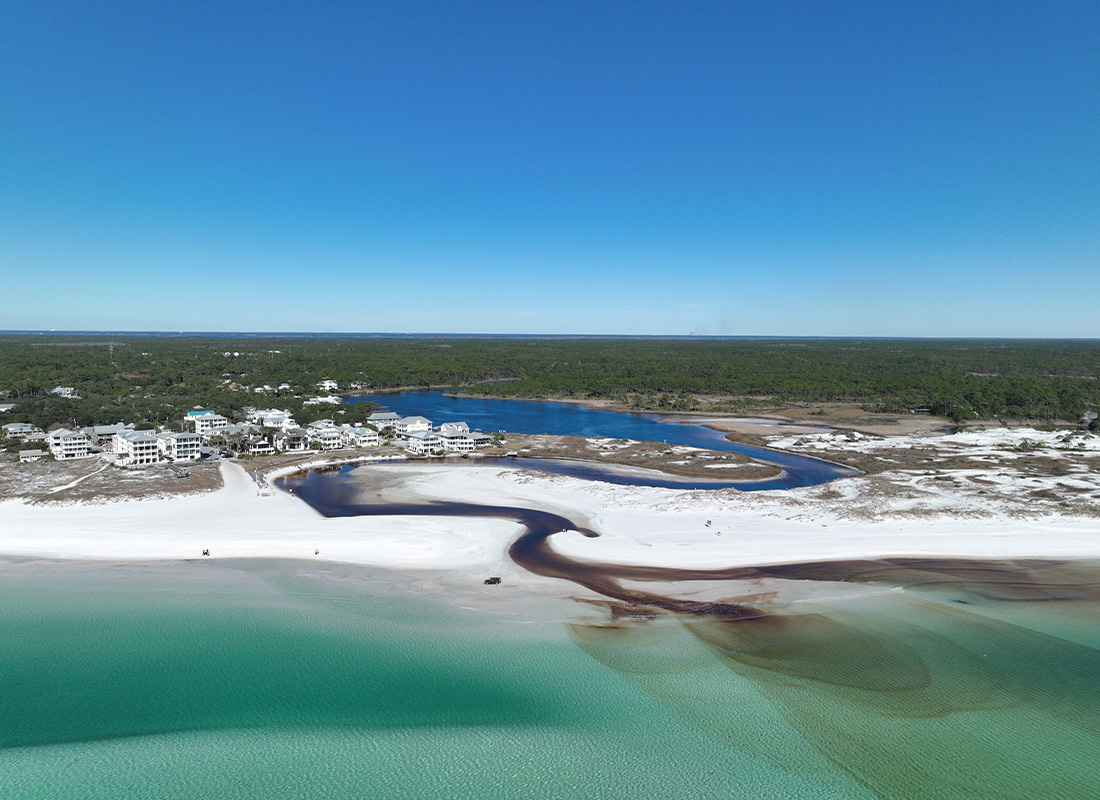
Walton County is home to 15 named coastal dune lakes along 26 miles of coastline — a rare feature found in only a handful of places on earth. These lakes connect to the Gulf through outfalls that open after heavy rain and storm surge, draining lake water to the Gulf and letting saltwater push back in. For homes around Western Lake near Grayton Beach and WaterColor, Eastern Lake, Camp Creek Lake, Deer Lake, and the others, that outfall is a real flood factor the standard conversation overlooks.
There’s a local advantage, too. Unincorporated Walton County holds a FEMA Community Rating System Class 6, which earns NFIP policyholders in the high-risk flood zone a 20 percent premium discount — a benefit private policies don’t carry. The current effective flood map (FIRM) for South Walton dates to December 30, 2020. Recent history is a reminder as well: Hurricane Sally in 2020 and Hurricane Michael in 2018 both brought surge, flooding, and evacuations to the Emerald Coast.
Vacation rentals and DP3 dwellings: don’t overlook flood
Coastal vacation rentals are the heart of what we insure. If your Gulf-front or dune-lake rental is a non-primary residence or a pure investment, the NFIP settles the building at actual cash value rather than replacement cost — a real shortfall on a high-value coastal property. The private forms we write can restore replacement cost and add loss of rental income and temporary living expenses the NFIP doesn’t include, which matter when a covered flood takes an income property offline. If your rental is a condo, the flood exposure is often a flood-related special assessment from the association rather than water inside your unit — review your association’s master flood policy for its terms, and ask us whether loss assessment coverage on a flood policy fits your situation.
Why Fuller Insurance for flood on the Emerald Coast
We’ve been an independent agency in Santa Rosa Beach since 2007, and flood is one of the coverages we know best. Because we represent multiple flood markets — private and NFIP — we can compare your options side by side and place coverage that fits your property, its location, and your budget. Call us at 850-622-5283 or request a flood quote, and we’ll rate it to your specific property.
Written by Garrett Fuller, owner and principal agent of Fuller Insurance LLC, a Florida-licensed insurance agent (FL License A091162 / NPN 600180 ).
Flood Insurance
Does my homeowners insurance cover flood damage in Santa Rosa Beach?
No — standard homeowners, condo (HO6), and renters policies exclude damage from flooding. That’s the market standard, which is why flood is written as its own policy, through either the federal NFIP or the private flood market. Fuller Insurance places both and compares them for your property.
Do I need flood insurance if my 30A home is in Zone X?
It’s usually not federally required in Zone X, but it’s still worth considering. According to the NFIP, about 29 percent of its flood claims from 2014 through 2024 came from lower-risk areas outside the mapped high-hazard zones, and FEMA notes that one inch of water can cause roughly twenty-five thousand dollars of damage. On 30A, a Zone X lot can sit a block from an AE or VE zone, so we rate each quote to the specific address.
Is private flood insurance better than the NFIP for a coastal Florida home?
It depends on the property. The NFIP caps building coverage at two hundred fifty thousand dollars and settles a non-primary residence’s building at actual cash value, while private forms we write — such as the Neptune Flood policies — can offer higher limits, replacement cost, and coverages the NFIP doesn’t include, like temporary living expenses and pool repair. The NFIP is still the better fit in some cases, especially where you can assume a grandfathered policy or qualify for Walton County’s community discount. Because private flood is frequently written by surplus-lines carriers that aren’t protected by the Florida Insurance Guaranty Association, we walk you through that tradeoff before you decide.
Does the Citizens flood insurance requirement apply to me?
If your property is insured by Citizens with wind coverage and your dwelling (Coverage A) is four hundred thousand dollars or more, flood coverage has been required since January 1, 2026. By January 1, 2027, that requirement extends to all Citizens personal-residential policies, regardless of flood zone. Condominium unit-owner and tenant-content policies are exempt. Confirm your status at your next Citizens renewal.
Will flood insurance cover lost rental income on my vacation rental?
The federal NFIP does not cover lost rental income or additional living expenses. Private flood forms we write can add loss of rental income and temporary living expenses, which matter when a covered flood takes an income property offline. For a Gulf-front or dune-lake rental held as a non-primary residence or investment, private coverage can also restore replacement cost on the building, where the NFIP would pay actual cash value.
How soon does flood insurance take effect, and can I buy it right before a storm?
A new NFIP policy generally takes 30 days to take effect, with limited exceptions such as coverage tied to a loan closing. Private flood often binds faster. But once a storm is named and watches or warnings go up for our area, most carriers stop writing new flood coverage until the threat passes — so the time to bind is before a storm is on the way, not while one is approaching.
Let’s Get Started
Flood Insurance Quote Request
"*" indicates required fields
Don’t like forms? Contact us at or email us.